Search funds find off-market businesses by writing directly to owners who match a one-page search brief, at a volume of several hundred to a few thousand letters and emails per search. They run referrals and broker deal flow beside that outreach. Stanford's data puts the typical search at about two years, so treat sourcing as a volume job with a weekly count.
Write the search brief before the first letter
Put the brief on one page: industries, revenue and EBITDA range, geography, the owner situation you want, and your role after closing. State what capital you have raised and what you have not.
Stanford's Search Fund Primer describes the traditional model: raise search capital from a group of investors, search full time, then raise acquisition capital for one company. Self-funded searchers skip the first raise and usually aim smaller, often under $2 million of EBITDA. Match the brief to your funding, because owners and brokers will ask.
A vague brief produces a vague list. "Business services in the Southeast" is not a brief. "Commercial HVAC service companies in Georgia and the Carolinas with $1 million to $4 million of EBITDA" is.
Build the owner list yourself
Direct outreach starts with a list you own. Pull companies from state registries, association directories, trade show exhibitor lists, and one data vendor. Then verify each one: still operating, who owns it, size in range.
Most searchers hire one to three interns or a part-time researcher to build and clean the list. In our experience a full-time search sends 500 to 3,000 owner letters and emails over its life, and needs at least 1,000 verified names to sustain that. If you are working one niche, the niche target worksheet gives you the columns to fill in.
Track every company in one pipeline, whichever route it arrived through.
Run three routes at the same time
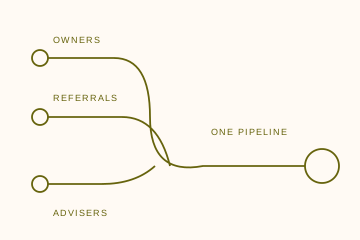
Direct owner outreach produces the deals with the least competition and the slowest replies. In our experience 1% to 5% of owners answer a mailed letter or email, and about a third of those take a call.
Referrals come from accountants, wealth managers, lawyers, and industry executives. Give each one your brief in two sentences and ask for one introduction. A referred owner answers at several times the rate of a cold one.
Brokers and advisors bring represented deals with a data room and a price expectation. Do not dismiss them; many searchers close a brokered deal after a year of cold letters. The broker deal flow guide shows how to get onto their lists.
Stanford's search fund research reports that roughly a third of searches end without an acquisition. Searchers who rely on one route are the ones who run out of time.
What should the owner letter say?
Subject: Question about [Company]
[First name],
I am [name]. I am looking to buy and run one [industry] company in [region]. I have committed search capital from [N] investors and will run the business day to day after a purchase.
[Company] came up because [one specific fact: years in business, service area, a customer review, an award]. I am not a broker, and I am not building a portfolio.
Would you be open to a 20-minute call about your business and what you would want in an eventual transition? If the timing is wrong, a one-line reply still helps me.
[Name, phone, email, one-line background]
Keep it under 150 words. Self-funded searchers replace the capital line with "I am funding this search myself and have lender relationships in place." Mail a printed letter, send an email two weeks later, then call. Do not guess the owner's age or retirement plans in writing. Stop after three touches unless the owner replies, and record a "no" so nobody on your team writes again.
Qualify replies in stages
A reply is not a deal. Stage one is a 20-minute call: what the business does, rough revenue, why the owner answered. Stage two is a longer conversation about goals, timing, and a price range. Stage three is a signed NDA and three years of financials.
Give each company one of four statuses: no interest, follow up on a date, fit unclear, or active. Suppose you have 40 replies from 1,200 letters. Expect about 12 first calls, four active conversations, and one or two that reach an LOI. Count only "active" when you report to investors.
Review the pipeline every week
Every Friday, count letters sent, replies, first calls, and active conversations by route. If 300 letters into one industry produced no calls, change the industry or the letter, not the volume. Searchfunder's community is a useful place to compare your reply rates with other searchers.
Where PrivSource fits: PrivSource is a deal network where qualified buyers, including search funds, apply for buy-side access and receive lower-middle-market opportunities from advisors and owners. It is one intermediated channel to run next to your direct letters, not a replacement for them.
Your letters make the market. The other routes catch what you would otherwise miss.